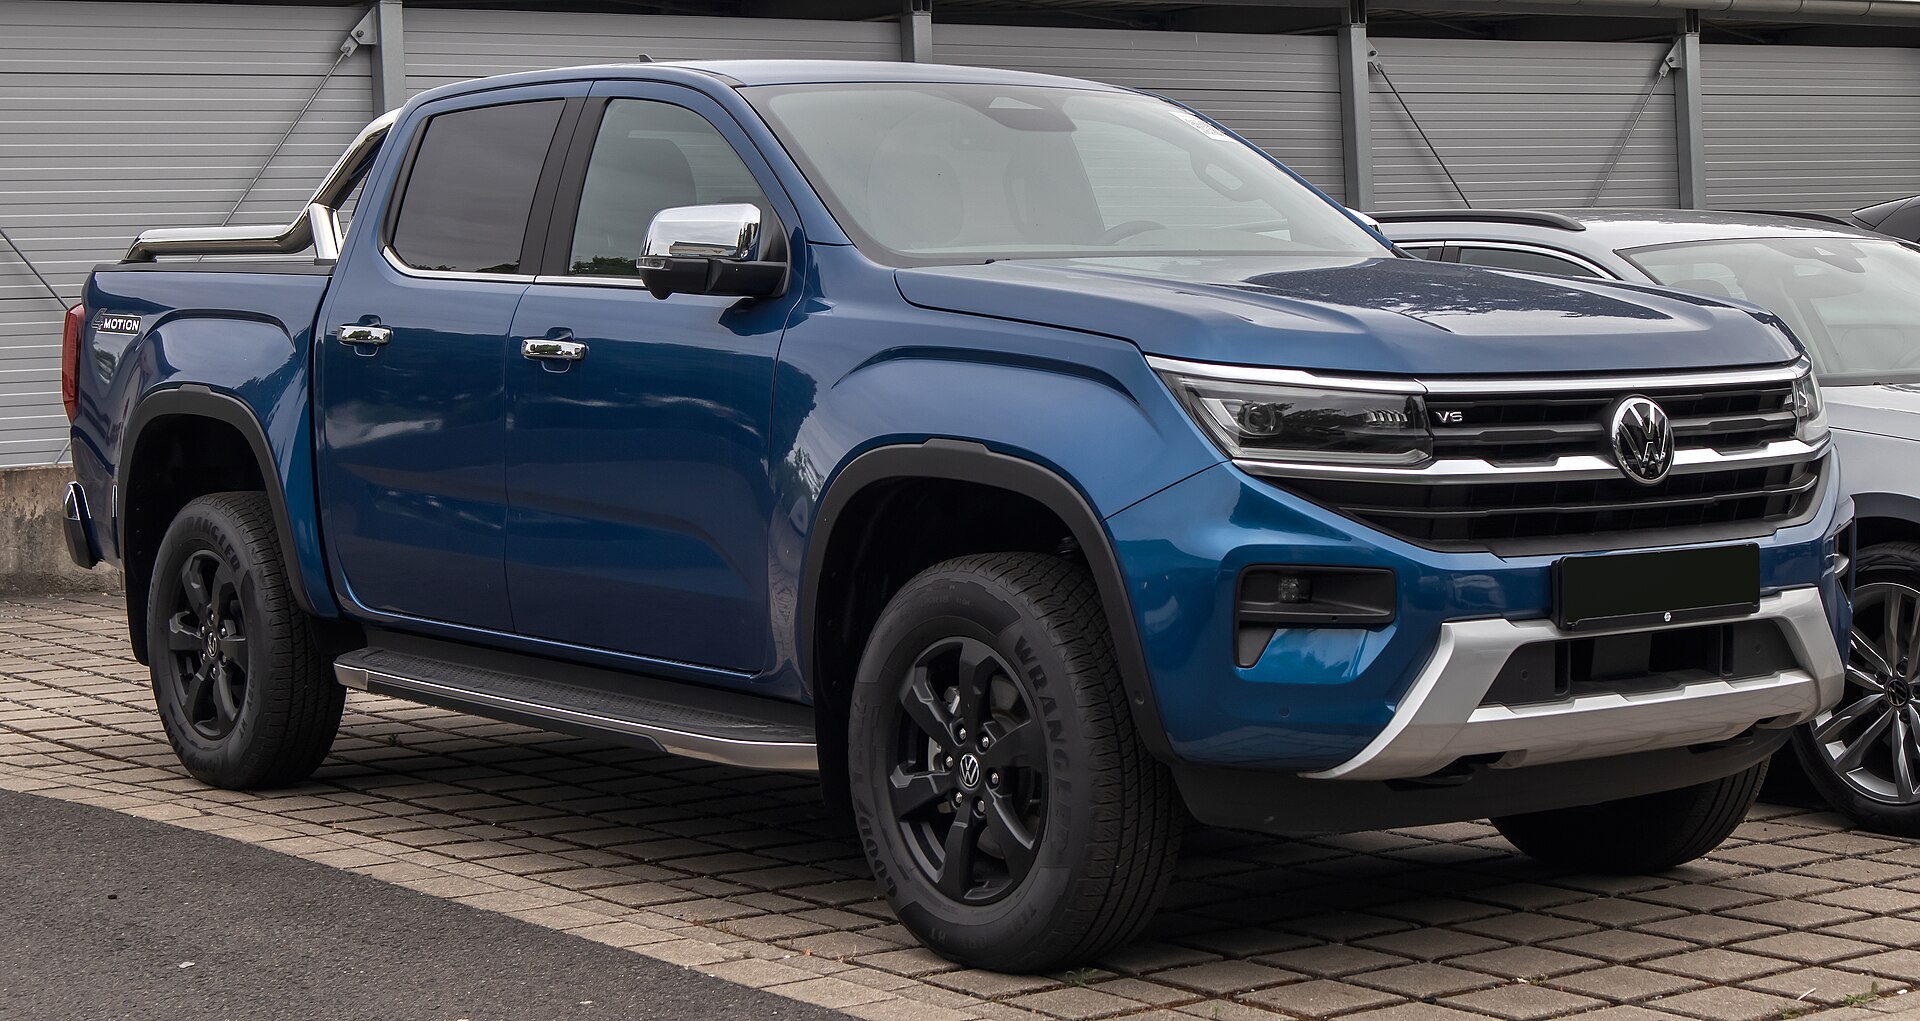
Amarok Finance for Australian Businesses
Businesses requiring premium dual-cab comfort, strong towing and executive-level presentation for client-facing teams.
Amarok is commonly funded through commercial structures where the ute is used primarily for business. Borrowers choose between ownership-first structures and cash-flow-first structures depending on tax position, replacement cycle and monthly budget.
Model-Specific Repayment Calculator
Start with realistic Amarok settings and adjust purchase price, deposit, balloon, term, frequency and new/used assumptions before lodging your quote.
Preloaded Amarok Settings
Typical price: $76,000 | Term: 3-7 yrs | Indicative rates: From 6.29%
Amarok Commercial Specifications (Finance Focus)
Typical drive-away range $68,400-$91,200 Payload Up to 1060kg Towing capacity 3500kg braked Drivetrain 4MOTION 4x4 Transmission 10-speed automatic Typical commercial buyers Project management, engineering consultancies, field sales, specialist trades.
Running Costs and Ownership Planning
Finance decisions should include whole-of-life ownership cost, not just monthly repayment.
Fuel economy 8.2-9.8L/100km Servicing $650-$1050 per interval Registration $1150-$1650/year Insurance and maintenance allowance Varies by postcode, driver profile and usage intensity Estimated annual ownership cost $12,200-$18,400 per year (fuel, rego, insurance, servicing)
Best Finance Structures for Amarok
Structure Best for Commercial notes
Chattel Mortgage Ownership and tax planning Common for GST-registered businesses claiming GST credits and depreciation. Finance Lease Cash-flow management Suitable where lease rentals and planned upgrade cycles are preferred. Operating Lease Fleet turnover and lower upfront burden Can suit businesses focused on usage and replacement cadence over ownership. Business Vehicle Loan Straightforward repayment structures Useful where simpler structures and predictable repayment schedules are needed.
Balloon payments, deposits, trade-ins and refinance pathways are tailored per lender and vehicle profile.
Eligibility and Documents
Borrower type: sole trader, company, trust or partnership with ABN
Business use evidence and asset suitability for the selected finance structure
Credit conduct review, including explanations for prior adverse events where applicable
Supporting evidence: ID, ABN details, bank statements, BAS/tax records (low-doc or full-doc route)
Asset checks: age, condition, sale type (dealer/private) and valuation if required
Real Borrower Scenarios
Scenario 1 Director-owned company financing an Amarok PanAmericana with a structured balloon for cash-flow control.
Scenario 2 Consulting business replacing an older SUV fleet with Amarok dual cabs for mixed metro and regional work.
Scenario 3 Trust borrower financing a dealer demonstrator Amarok with full-doc support.
FAQs Is Amarok finance available for trusts? Yes, trust borrowers are commonly supported with the right trustee and financial documentation.
Can I finance a demonstrator Amarok? Yes. Dealer demonstrators are often financed as used assets with near-new profiles.
Does a premium ute change lender policy? Pricing and policy can vary with vehicle value, but many lenders actively fund premium dual-cab utes.
Can I include accessories and protection packs? Usually yes where items are invoiced and approved by lender policy.
Is a balloon recommended? Many businesses use a balloon to lower monthly payments while preserving operating capital.
Can I refinance before term end? Yes, refinance or restructure options are available subject to payout terms.