How Ute & Commercial Vehicle Finance Works
Whether you're a tradie needing a HiLux for site work, a courier running a Sprinter van, or a farm manager adding a Ranger to the fleet, ute and light commercial finance can spread the acquisition cost over an agreed term. The available term depends on the applicant, vehicle and lender policy.
The amount financed, evidence and structure are transaction-specific. Eligible business-use GST credits, interest, lease costs, depreciation or write-offs depend on current law and your circumstances; confirm tax treatment with a registered tax adviser.
Australian ute market evidence
Before comparing finance, review AFA’s Australian Ute Market Monitor for registered fleet age, state mix and monthly model activity. It uses a published model taxonomy and does not treat every light commercial vehicle as a ute.
Vehicles We Cover
- Dual-cab utes — Toyota HiLux, Ford Ranger, Nissan Navara, VW Amarok, Isuzu D-MAX, Mitsubishi Triton
- Single-cab and cab-chassis utes for trade/farm use
- Light commercial vans — Toyota HiAce, Ford Transit, Mercedes Sprinter, Hyundai Staria Load
- 4WD wagons with commercial use — Toyota LandCruiser, Prado, Ford Everest
- New and used vehicles, subject to lender age, condition and end-of-term policy
Popular Utes We Finance
Choose a detailed model guide where one is available, or start a model-specific quote for newer and specialist utes.
Still choosing the vehicle before you structure the business finance? Browse current utes and indicative repayment estimates at BaseRate, another Velocity Works service focused on vehicle research and car finance.
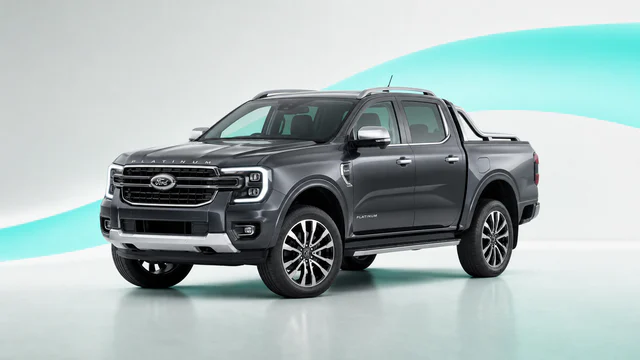
Ford Ranger Finance
Commercial finance pathways for Ranger buyers, contractors and fleets.
Read the guide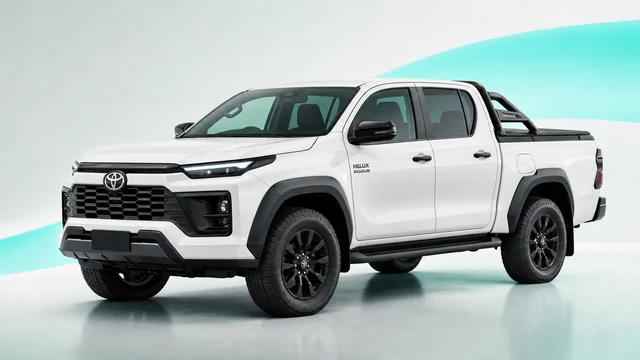
Toyota HiLux Finance
Compare structures for HiLux work, trade and business use.
Read the guide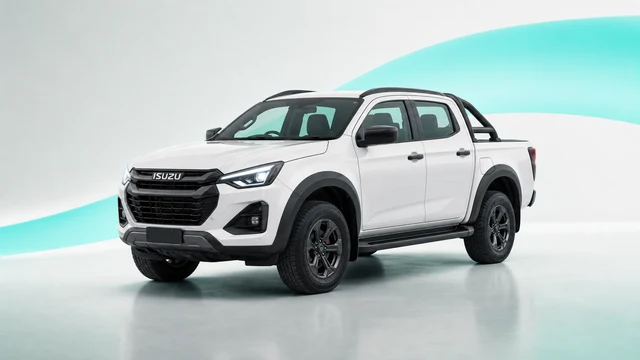
Isuzu D-MAX Finance
Ownership and lease options for work-focused D-MAX buyers.
Read the guide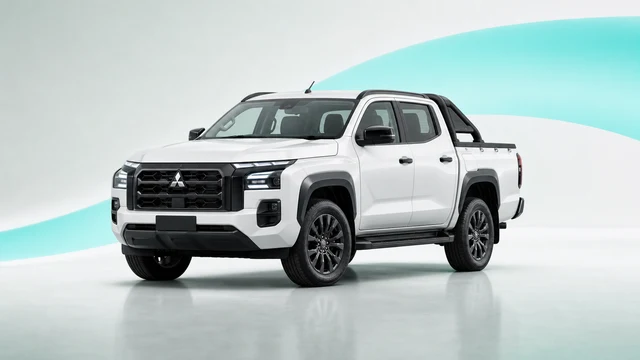
Mitsubishi Triton Finance
Commercial repayment and lender pathways for Triton buyers.
Read the guide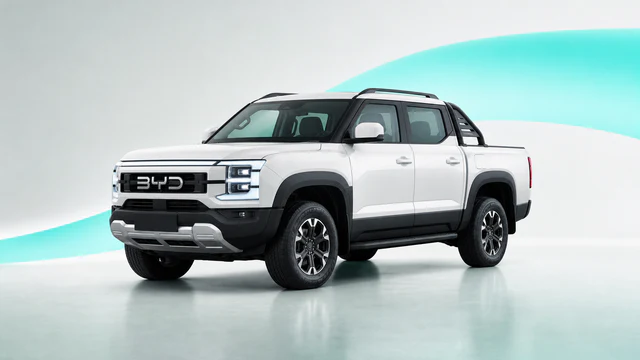
BYD Shark 6 Finance
Compare business finance structures for the plug-in hybrid Shark 6.
Compare finance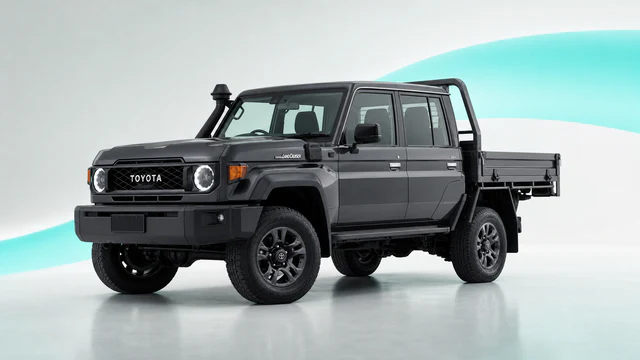
LandCruiser 70 Finance
Finance options for trade, agricultural and regional business use.
Compare finance
GWM Cannon Finance
Compare commercial structures for Cannon purchases and upgrades.
Compare finance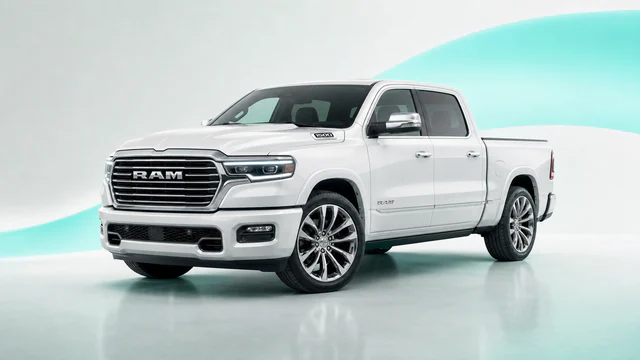
RAM 1500 Finance
Structure finance for a full-size pickup used in business.
Compare finance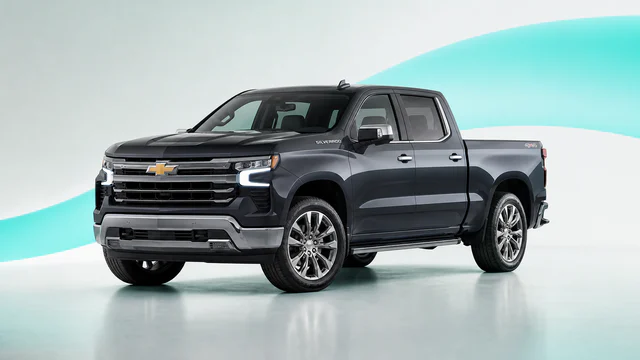
Chevrolet Silverado Finance
Commercial finance options for heavy-duty towing and work use.
Compare finance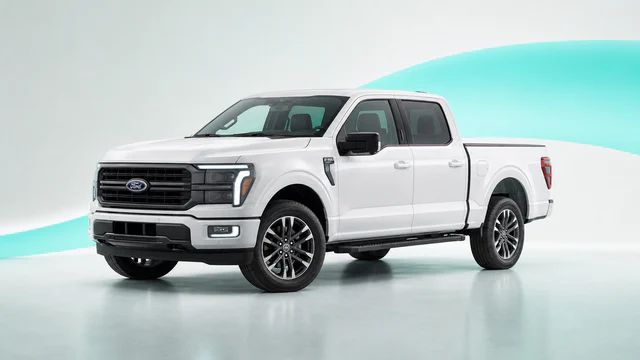
Ford F-150 Finance
Compare finance structures for full-size F-150 business use.
Compare financeMore Model Finance Guides
Nissan Navara Finance
Commercial lender options for Navara purchase and replacement cycles.
VW Amarok Finance
ABN-focused finance structures for premium ute buyers.
Mazda BT-50 Finance
Business vehicle financing for BT-50 applications.
LDV T60 Finance
Cost-focused commercial pathways for LDV T60 borrowers.
Borrower & Scenario Guides
These pages focus on policy and structuring for common commercial ute borrower profiles and deal structures.
Ute Finance for Sole Traders
ABN evidence, income docs, and structure choices for sole traders.
Ute Finance for New ABN
Startup pathways, policy limits, and deposit strategy.
Low Doc Ute Finance
Commercial low-doc options for self-employed applicants.
Used Ute Finance
Age limits, valuation controls, and risk factors.
No Deposit Ute Finance
When lenders may consider full-funding scenarios.
Business Vehicle Pathways for Ute Buyers
If your ute decision is tied to company ownership, trust setup, private-sale purchase, or broader fleet planning, continue through the relevant guide below.
Business Ute Finance
Move from the ute guide into the full vehicle-finance pathway set.
Ute Finance for Companies
Company-owned vehicle and director guarantee scenarios.
Ute Finance Through Trusts
Trustee borrower setup and asset ownership guidance.
Private Seller Vehicle Finance
How private-sale ute purchases are financed and settled.
Dealer vs Business Finance
Channel comparison before you commit at dealership stage.
New vs Used Vehicle
Condition, policy and repayment trade-offs.
Ready to Compare Your Options?
Review the ownership, lease and end-of-term differences before choosing a structure.
Compare Structures →What Determines a Ute Finance Rate?
A useful rate comparison must use the same applicant, vehicle, seller, amount, term, deposit, balloon and fees. An advertised rate without those inputs is not enough to compare total cost.
| Input | Why it matters |
|---|---|
| Business and credit profile | Trading history, evidence and existing commitments affect policy and pricing. |
| Vehicle and seller | Age, condition, kilometres, dealer or private sale can change term and valuation requirements. |
| Structure and term | Fees, repayment frequency and any balloon or residual change total amount payable. |
Compare a written offer using the interest rate, fees, scheduled repayments, final payment and total amount payable. Read the rates guide →
Finance Structures for Utes & Commercial Vehicles
The right structure depends on your GST registration, how much you use the vehicle for business, and whether you want to own it at the end.
| Feature | Chattel Mortgage | Finance Lease | Operating Lease |
|---|---|---|---|
| Ownership | Immediate | At end of term | Return to lessor |
| GST | Potential eligible credit on purchase | Potential credits on rentals | Potential credits on rentals |
| Depreciation | Potential business-use deduction | Check tax treatment | Check tax treatment |
| Interest / rentals | Business-use interest may be deductible | Eligible rental costs may be deductible | Eligible rental costs may be deductible |
| Balloon / Residual | Optional | Mandatory | Built-in |
| Best For | GST-registered tradies & businesses | Cash flow optimisation | Short-term fleet use |
Chattel Mortgage
You own the ute from settlement while the lender takes security. Eligible GST-registered businesses may claim the creditable business-use portion of GST, while eligible interest and depreciation may be deductible. A balloon reduces scheduled repayments but increases the final amount and usually the total interest.
Finance Lease
The financier owns the vehicle and leases it to you. Eligible business-use lease costs may be deductible. Check the residual, end-of-term options, accounting treatment and tax treatment before comparing it with ownership finance.
Operating Lease
Think of it as a long-term rental. You normally return the vehicle at the end, subject to the contract's kilometre, condition and return rules. It can suit regular fleet replacement, but the lowest scheduled payment is not necessarily the lowest total cost.
Eligibility Requirements
Eligibility is lender- and transaction-specific. Common assessment inputs include:
- Applicant identity, legal entity and active business details
- Trading history, industry and existing commitments
- Credit conduct and the lender's current scorecard
- BAS, bank statements, financial statements or other evidence requested for the pathway
- Vehicle quote or invoice, seller details, age, condition and intended business use
Alternative-document pathways can exist, but "low doc" does not mean no evidence and does not guarantee approval.
Tax Considerations for a Work Ute
Tax outcomes depend on the owner, structure, vehicle type, cost, business-use proportion and rules for the relevant income year:
- Instant Asset Write-Off: May apply to the taxable-purpose portion of an eligible asset where the current threshold and timing rules are met
- Depreciation: May apply where the business owns an eligible depreciating asset
- Interest Deductions: The eligible business-use portion of interest may be deductible
- GST Input Credit: GST-registered businesses may claim an eligible business-use credit, subject to car limits and other rules
- Lease Deductions: Eligible business-use lease costs may be deductible
- FBT Consideration: If the vehicle is used privately, Fringe Benefits Tax may apply — review with your accountant
Note: Tax outcomes depend on your circumstances, business-use percentage and the rules for the relevant income year. Confirm them with a registered tax adviser.
Model the Repayment Before You Apply
Stress-test the amount, deposit, term, balloon and example rate without creating a lender application.
Estimate Repayments →Ute Finance FAQs
Ute Finance by State
Lender rates are set nationally, but local dealer networks and broker availability can vary by region. Use state-specific guidance for your area.
Vehicle Finance NSW
Sydney, Newcastle, Wollongong & regional NSW
Vehicle Finance VIC
Melbourne, Geelong, Ballarat & regional Victoria
Vehicle Finance QLD
Brisbane, Gold Coast, Cairns & regional Queensland
Vehicle Finance WA
Perth, Fremantle, Kalgoorlie & regional WA
Vehicle Finance SA
Adelaide & regional South Australia
Vehicle Finance ACT
Canberra & surrounds
Vehicle Finance TAS
Hobart, Launceston & regional Tasmania
Vehicle Finance NT
Darwin, Alice Springs & the Northern Territory